How Home Insurance Deductibles Work, Including Wind and Hail
Your policy may have two or three deductibles, and one of them may be a percentage of your home's insured value. Here's how to read them.
A deductible is the part of a covered loss that you pay yourself. With home insurance, it's subtracted from the claim payment. If a covered repair costs $12,000 and your deductible is $2,000, the insurer pays $10,000.
That part is simple. What trips people up is that a home policy can have more than one deductible, and they aren't all calculated the same way.
Flat-dollar deductibles
The standard deductible, sometimes called the "all other perils" deductible, is usually a fixed amount. Common choices are $500, $1,000, $2,500 and $5,000. It applies to most claims: fire, theft, a burst pipe.
Percentage deductibles
Some deductibles are set as a percentage of your dwelling coverage, not as a dollar amount. They typically range from 1% to 5%, and can be higher in high-risk areas.
The math matters, because the percentage is taken from your coverage limit, not from the size of the claim:
- Dwelling coverage of $300,000 with a 1% deductible: you pay the first $3,000.
- Dwelling coverage of $400,000 with a 2% deductible: you pay the first $8,000.
- Dwelling coverage of $500,000 with a 5% deductible: you pay the first $25,000.
As your dwelling limit goes up over time, a percentage deductible goes up with it.
Wind, hail and hurricane deductibles
Percentage deductibles show up most often for storm damage:
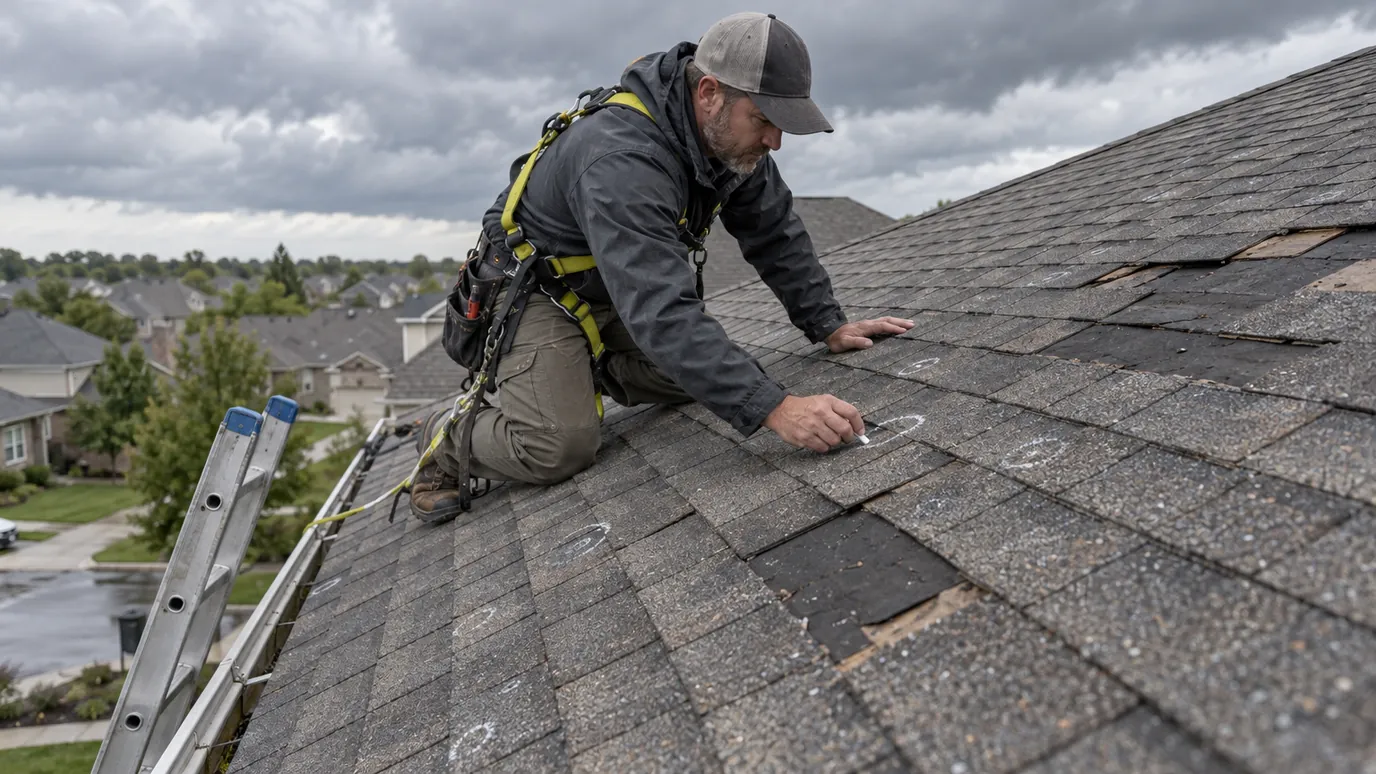
- Wind and hail deductibles are common in the Plains, the Midwest and parts of the South, where hailstorms and tornadoes produce a lot of roof claims.
- Hurricane or named-storm deductibles are used in many Atlantic and Gulf Coast states. They apply only when a specific trigger is met, such as a storm being named or a hurricane warning being issued by the National Weather Service. The trigger is defined in your policy and by state rules.
In some areas these are mandatory. In others you can choose between a flat amount and a percentage, at different prices.
What doesn't have a deductible
Deductibles apply to damage to your own property. Liability claims and medical payments to others generally don't have one.
How to choose
- Pick an amount you could actually pay. A higher deductible lowers your premium, but only helps if you could cover it from savings after a loss.
- Price the difference. Ask for the premium at two or three deductible levels. Going from $1,000 to $2,500 sometimes saves a meaningful amount per year, and sometimes very little.
- Think about small claims. Filing claims can affect your future premiums. Many homeowners prefer a higher deductible and pay for small repairs themselves, keeping insurance for the big losses.
- Check your lender's rules. Mortgage lenders often set a maximum deductible, commonly a percentage of your dwelling coverage.
Find these on your declarations page
- Your standard (all other perils) deductible
- Any separate wind, hail, hurricane or named-storm deductible
- Whether each one is a dollar amount or a percentage
- For a percentage, the dollar amount it works out to today
- Separate deductibles on flood or earthquake policies, if you have them
The bottom line
Know every deductible on your policy and what each one comes to in dollars. And when you compare quotes, make sure a lower price isn't just a higher storm deductible.
Note: This article is general information, not insurance, legal or financial advice. Coverage, requirements and pricing vary by state and insurer; check your policy and your state's insurance department.